Quick Summary: Exercising Incentive Stock Options (ISOs) can build significant wealth for tech professionals, but holding the shares exposes them to the Alternative Minimum Tax (AMT) “phantom income” trap. The AMT system taxes the Bargain Element—the spread between your strike price and the 409A value at exercise—even if you haven’t sold a single share. Tech workers can legally minimize this tax risk by calculating their AMT crossover point to stagger exercises, executing a Disqualifying Disposition if the stock price drops before year-end, and utilizing IRS Form 8801 to reclaim banked Minimum Tax Credits (MTC) in future tax years
Navigating the ISO & AMT Tax Trap: A Guide for Silicon Valley Tech Employees
For Silicon Valley engineers, startup founders, and tech executives, receiving Incentive Stock Options (ISOs) is one of the most lucrative wealth-building opportunities available. Under regular federal income tax rules, exercising an ISO and holding the shares is a non-taxable event. You don’t pay ordinary income tax when you exercise—only capital gains tax when you eventually sell.
However, this tax-deferred treatment conceals a dangerous financial hazard: the Alternative Minimum Tax (AMT) ISO tax trap.
Without proper scenario modeling, tech professionals frequently exercise ISOs, hold the shares, and suddenly face tens of thousands of dollars in “phantom” income taxes due to the IRS—even if the stock price crashes before they sell a single share.
Here is a guide on how the ISO AMT tax trap works, how to calculate your AMT crossover point, and how to recover your taxes using Minimum Tax Credits (Form 8801).
1. What Is the ISO “Bargain Element” Phantom Income?
When you exercise an ISO, the difference between the Fair Market Value (FMV / 409A valuation) on the exercise date and your Strike Price is known as the Bargain Element (or “spread”):
Bargain Element = (FMV at Exercise – Strike Price) x Number of Shares Exercised
While the regular tax code ignores this spread at exercise, the AMT system treats the Bargain Element as income in the year of exercise.
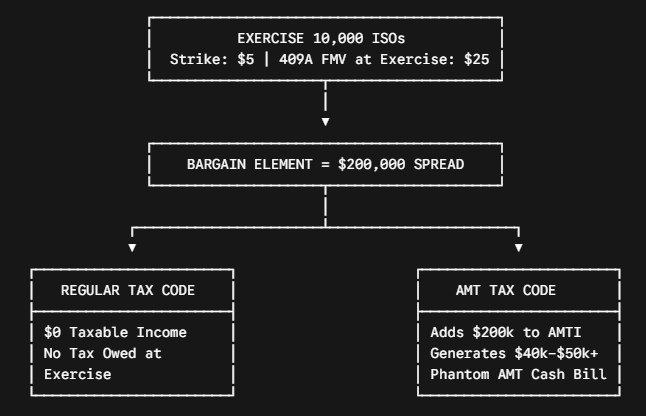
If your tentative minimum tax under the AMT system exceeds your regular tax liability, you must pay the difference in cash to the IRS—even though you haven’t sold any stock to generate cash proceeds.
2. The Disaster Scenario: Stock Price Plummets After Exercise
The real danger occurs when tech employees hold exercised shares through a market downturn.
Example: You exercise ISOs with a $200,000 bargain element. The IRS assesses an estimated $50,000 AMT bill. In April, when taxes are due, the private market or stock price drops 80%. Your stock is now worth only $30,000 total—yet you still owe $50,000 in cash taxes to the IRS.
This cash-flow mismatch has forced unprepared employees into liquidating personal assets or entering IRS installment plans to settle tax debts on stock that lost value.
3. Strategies to Avoid or Mitigate the AMT Tax Trap
1. Model Your “AMT Crossover Point”
You do not owe AMT on every ISO exercise. Every taxpayer has an AMT Exemption. You can exercise a specific dollar threshold of ISO spread each tax year before your tentative minimum tax exceeds your regular income tax. Staggering exercises over 2–3 tax years allows you to absorb shares without triggering AMT.
2. Time Exercises Early in the Calendar Year
Exercising ISOs in January or February gives you 11+ months to monitor the company’s stock price or 409A valuation. If the stock plummets later in the year, you can execute a Disqualifying Disposition (selling or transferring the shares before December 31st). This eliminates the AMT calculation and converts the actual gain into ordinary income tax, preventing you from paying tax on phantom paper gains.
3. Recover Taxes via the Minimum Tax Credit (Form 8801)
The good news: AMT paid on ISO exercises is not permanently lost. It generates a Minimum Tax Credit (MTC). In future tax years—especially the year you finally sell the ISO stock and recognize a regular capital gain—you use IRS Form 8801 to claim that banked credit back, reducing your regular tax bill.
4. How S-Corps & PTE Tax Options Complement Tech Advisory
If you consult alongside your tech job, operate a 1099 advisory practice, or hold equity in an S-Corporation, integrating California PTE Tax (AB 150) and entity planning helps offset broader personal tax exposure.
Learn how our San Jose Small Business Tax Accountant team coordinates equity compensation with business entity structuring.
Optimize Your Stock Option Strategy Today
Exercising Incentive Stock Options without modeling AMT risk is an unnecessary financial gamble.
At Moontree Tax Service, we specialize in equity compensation planning, AMT crossover projections, Form 8801 credit tracking, and tax compliance for tech professionals across Silicon Valley (San Jose, Santa Clara, Sunnyvale, Mountain View, Palo Alto).
Schedule an Equity Strategy Consultation with a San Jose CPA Today or call us directly at (408) 475-2306.
Disclaimer: This article is intended solely for educational and informational purposes and does not constitute formal legal, accounting, or tax advice. Tax laws change frequently and apply differently based on individual financial profiles and equity agreements.